Is a Rolex Loan Basically a Pawn Shop Thing, or Something Different?
It’s Thursday afternoon in Scottsdale. You’re planning to bid at an auction during Barrett-Jackson week, or you’ve got a purchase coming up at WestWorld of Scottsdale, and some of your cash is tied up in a Rolex. Selling the watch might solve the timing problem, but you may not want to part with it for good. So you start looking at a loan using the watch as collateral.
Is that just a pawn shop transaction with a nicer watch? Sometimes the basic idea is similar: you hand over an asset, receive money, and get the asset back if you repay under the agreed terms. But the lender, valuation process, loan structure, customer experience, and costs can differ substantially.
The short answer: a watch collateral loan is a form of asset-backed borrowing, and some pawn lenders offer it. But not every collateral loan works like the quick, walk-in transaction people picture when they hear “pawn shop.” The details matter more than the label.
Start with the basic distinction: pawn vs collateral loan
Both arrangements use property to secure a loan. The watch is collateral: if you fail to repay according to the contract, the lender may have rights to sell it to recover what’s owed. But “pawn vs collateral loan” is not a choice between one legal universe and another. A pawn loan is itself a type of loan secured by property. The practical differences are usually about how the loan is evaluated and managed.
A traditional pawn transaction may be built for speed and convenience. You bring in an item, get an offer, and may have a short, clearly stated period to repay or renew. A specialist luxury-asset lender may put more emphasis on the specific reference, condition, completeness, market evidence, and a tailored loan arrangement. That does not automatically mean a better offer or lower cost. It means you should compare the actual terms and process.
Question What to compare How is the watch valued? Ask whether the estimate reflects the exact model, condition, accessories, and current market evidence—or relies mainly on a broad category. What will I receive? Get the proposed loan amount in writing and understand how it relates to the lender’s valuation. What will it cost? Review interest, fees, minimum charges, renewal terms, and the total repayment amount by a specific date. What happens to my watch? Confirm how it is documented, stored, insured, and returned after repayment, and what happens if you miss a deadline.Here is the tradeoff. A fast, private loan may be useful when timing matters, but convenience does not make the cost disappear. Compare the dollars and deadlines, not just the service style.
Why a Rolex can work as collateral
Rolex is widely recognized, actively traded, and supported by a substantial secondary market. That makes many Rolex models more straightforward to evaluate and potentially resell than an unfamiliar or highly specialized luxury item. In lending terms, that market activity can make a Rolex a relatively liquid luxury asset.
“Liquid” does not mean every Rolex can be turned into cash instantly at a predictable price. Model, reference, age, condition, originality, service history, box and papers, and current demand can all affect the number. A watch with visible damage or replaced parts may be treated differently from a comparable example in stronger condition. Two watches that look similar across a table can have different market appeal.
For pricing context, a lender or evaluator may look at global secondary market pricing tracked publicly, along with relevant sales and current market signals. Public listings are useful information, but an asking price is not the same as a completed sale, and neither one automatically determines a loan offer. A lender also has to consider its own costs, risk, and ability to recover the amount advanced if repayment does not happen.

That is why a collateral valuation and a retail replacement estimate can differ. A loan offer is not a promise that the watch would sell for the same amount in a private sale, at a dealer, or at auction.
What happens in authentication and valuation?
A credible authentication and valuation process should be more than a quick look at the dial. The exact steps vary by provider, but you should expect the person assessing the watch to establish what it is, evaluate its condition, and explain the basis for the proposed loan amount.
Identity and authenticity
The evaluator may inspect identifying marks, case and bracelet details, movement characteristics, and whether components appear consistent with the reference. A box or papers can help document a watch’s history, but they do not replace examination of the watch itself. Ask what happens if authentication is uncertain and whether additional review is required.
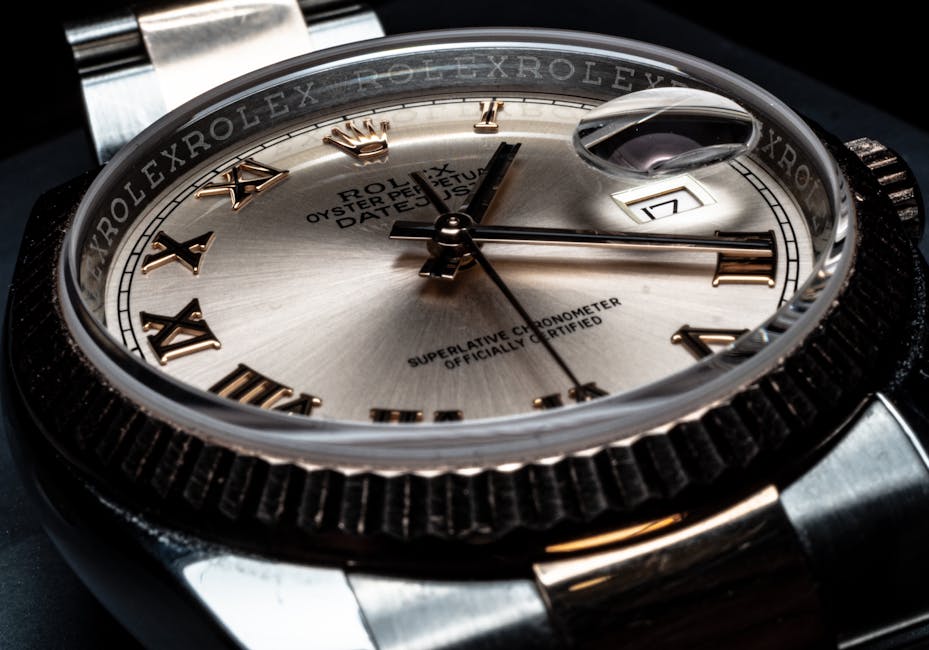
Condition and completeness
Expect attention to the case, bracelet, clasp, dial, crystal, movement function, and signs of polishing, repair, or replacement parts. Box, papers, service records, and extra links may matter to the assessment, even though they do not all carry the same weight. Be candid about known issues. A surprise discovered during inspection can change the assessment or delay a decision.
Market context and loan amount
Ask which market references were considered and how they relate to the specific watch in front of the evaluator. Then separate three numbers that people often blur together: estimated market value, possible sale proceeds, and the loan amount. They are not interchangeable.
Before you hand over the watch, ask for written terms covering the loan amount, fees, interest, due dates, renewal or extension options, and the consequences of nonpayment. Also ask how the watch will be held and documented. Clear answers are part of the process, not an awkward favor.
Why borrow against a watch instead of selling it?
A watch collateral loan can free cash while leaving you a path to recover the watch after repayment. That can be useful when you have a temporary gap between money coming in and money going out. You might need funds for a business expense, a tax bill, or a purchase that cannot wait for a slower sale process.
It can also appeal to someone who wants to avoid publicly listing a valuable watch or arranging showings and negotiations with buyers. A private transaction may reduce the number of people involved, but “private” should still mean clear documentation and careful custody. Ask who will have access to the watch and how the loan and collateral are recorded.
In Arizona, collectors sometimes have several expensive interests competing for the same cash. If you are considering a car during Barrett-Jackson week, for example, borrowing against a Rolex might look like a way to preserve cash for bidding without selling a watch you intend to keep. That decision only makes sense if the loan’s full cost and repayment plan fit your finances. Don’t borrow against a watch simply because the event is exciting or the lender can move quickly.
Speed and privacy versus the interest-rate tradeoff
Luxury asset lending is often considered when a borrower values access to cash and a direct process. Depending on the provider and the watch, a decision may be faster than arranging a conventional loan or finding a buyer. But timing is not guaranteed. Authentication, documentation, lender review, and any required transfer or inspection can take time.
Interest and fees are the other half of the decision. A short-term loan can have a meaningful cost even when the borrowed amount seems modest. Find out the total amount due on a calendar date—not just a rate quoted without context. Ask whether interest accrues daily or monthly, whether there are origination or storage fees, what a renewal costs, and whether paying early changes the amount due.
Compare that total with your alternatives: selling the watch, using cash, delaying the purchase, or arranging another type of credit. A bank credit line is not the same thing as an asset-backed loan. A bank may evaluate credit history, income, and other factors; a watch-backed lender focuses substantially on the pledged asset and the terms of that loan. Each can have different timelines, underwriting, costs, and consequences.
Privacy and speed have value, but they are not a substitute for affordability. If your repayment plan depends on a hoped-for sale, bonus, or market move, be honest about what happens if that money arrives late.
Auction-week planning: do the math before the bid
Auction week is a particularly bad time to make a rushed borrowing decision. The schedule can be packed, the bidding atmosphere can make a purchase feel urgent, and the watch may need to be inspected before a lender can finalize anything. Plan before you are standing near a car you want to bid on.
- Set the total cash need. Include the purchase price, buyer’s premium, taxes, transport, and any immediate costs. Do not plan only around the hammer price.
- Ask for terms early. Contact the lender before auction week if possible. Request the expected timing, required documents, loan amount, full cost, and repayment deadline in writing.
- Allow time for authentication. A watch that needs additional review may not fit a same-day plan. Bring the watch and any documentation the provider requests.
- Set a repayment source and date. Identify where repayment will come from and when. “I’ll sort it out after the event” is not a plan.
- Keep a fallback. Decide in advance what you will do if the loan is smaller, slower, or more expensive than expected. The fallback may be a lower bid—or no bid.
At a large event such as Barrett-Jackson near WestWorld of Scottsdale, the best time to evaluate financing is before the auction calendar starts to control your decisions. A watch loan should support a planned cash-flow decision, not turn a last-minute impulse into a long-term cost.
Questions to ask a watch lender
- Who authenticates the watch, and what parts of the watch are examined?
- How do you determine the valuation, and what market evidence do you use?
- What is the exact loan amount and the total amount due on my planned repayment date?
- Are there origination, storage, insurance, late-payment, or renewal fees?
- How long does the process typically take after you receive the watch and documents?
- How is the watch stored, insured, and documented while it is in your custody?
- What are the deadlines, extension options, and consequences if I cannot repay?
- Can I repay early, and if so, how is the payoff amount calculated?
Providers such as Diamond Banc are part of the luxury-asset lending market, but you should evaluate any company on its written process and terms—not on the category name or a broad promise about value. Ask for the same facts from each provider so you can compare like with like. A transparent evaluator should be able to explain how authentication works, what supports the valuation, and what your obligations will be.
So, is it basically a pawn shop thing?
It shares the core structure of a pawn loan: an asset secures borrowing, and the borrower has to meet the contract terms to get that asset back. But a Rolex-backed loan may involve specialist luxury-watch authentication, reference-specific market research, more tailored handling, or a different loan structure. Those differences are worth checking; they are not automatic guarantees of a higher offer, lower rate, or better outcome.
The right question is not gmt-master II resale whether the transaction sounds like a pawn shop. It is whether the lender can authenticate and value your exact watch, explain the full cost and timeline, protect the collateral appropriately, and give you terms you can repay.
If it is Friday night before an auction, and you are deciding whether to borrow against the Rolex in your safe, pause long enough to read the due date and calculate the payoff. A watch can be a useful source of liquidity without being money in the bank. Borrow only when the timing, total cost, and repayment plan make sense—even if that means walking away from the bid.